Learn to live off the land at the Freedom & Prosperity Rally!
April 6, 2024 | St. Cloud, Florida | 9 AM - 5:30 PM EST
We will be short-staffed for the Holidays. If you encounter difficulty reaching us by phone, kindly leave a detailed voicemail, and we'll promptly return your call. Alternatively, you can contact us via email at questions@freedomlawschool.org.

In 1992, Peymon Mottahedeh uncovered the staggering truth that 99% of American’s are NOT LEGALLY OBLIGATED to pay Federal Income Tax. Peymon founded Freedom Law School (FLS) in 1996 as a mission to spread this truth & liberate fellow American’s from the blatant DECEPTION, robbery, & slavery of the American People by the IRS.
FLS’s main goal of EMPOWERING American’s to be FREE is accomplished by EDUCATING them, the importance of which is characterized by the following quotes from our 3rd President, Thomas Jefferson…
“An educated citizenry is a vital requisite for our survival as a free people.” -- Thomas Jefferson
“If a nation expects to be ignorant and free, in a state of civilization, it expects what never was and never will be.” -- Thomas Jefferson
We believe as more Americans understand their rights & the law, the better equipped we are to defend the very LIBERTY our Founding Fathers fought & died for. We provide a PRACTICAL STEP for American’s to fight back against the CORRUPT Government by empowering Americans to keep the money they EARN rather than paying Washington taxes THEY NEVER OWED IN THE FIRST PLACE.
We uncover the misconception of the IRS being some powerful entity armed with the capacity to track each American, & instead PROVE the IRS as a highly dysfunctional, weak, incompetent, & disorganized BUREAUCRACY if you stop filing 1040 income tax confession forms. We teach you to strictly follow the law as published on U.S. Government Official Legal Websites including tax laws passed by Congress, U.S. Treasury regulations, & U.S. Supreme Court Decisions as well as the 1040 income tax form & it’s instructions. By following this system over the past 30+ years, NO STUDENT has ever had any of their pay checks levied, bank accounts seized, or been imprisoned for not filing & paying Federal Income Taxes. Become a modern-day Founding Father today by learning more here…
There is a tiny portion of the population that is required to file and pay federal income taxes. To identify if you are among that tiny portion, we must first take a look at 26 USC 79(a), which is Title 26 (the Internal Revenue Code) of the United States Code, in Chapter 79 (Definitions). Here we will look at both definitions of the“United States” and “State,” and how they should be used within the context of this chapter.
(9) United States
"The term 'United States' when used in a geographical sense includes only the States and the District of Columbia."
Notice that the term “United States” is defined as including the States and DC. Well, what does “State” mean? It gives us a definition for that too…
(10) State
"The term 'State' shall be construed to include the District of Columbia, where such construction is necessary to carry out provisions of this title."
The term “State” is defined as including D.C., but it doesn’t name any other states. Meese v. Keene (1987) that legal definitions exclude unstated meanings of that term, and from the Stenberg v. Carhart (2000) Supreme Court decision that "when a statute includes an explicit definition, we must follow that definition, even if it varies from that term’s ordinary meaning". We also know that “includes” can be synonymous with “means” from the Supreme court case Helvering v. Morgan’s, Inc. (1934).
In addition, the “United States” is defined in several other legal texts as well. Notice Title 8’s definition of “United States” in 8 USC 1101, which deals with Aliens and Nationality says:
"(38) The term 'United States', except as otherwise specifically herein provided, when used in a geographical sense, means the continental United States, Alaska, Hawaii, Puerto Rico, Guam, the Virgin Islands of the United States, and the Commonwealth of the Northern Mariana Islands."
And the definition of “United States” from 26 USC 4612, which deals with the taxation of petroleum and crude oil says:
"The term 'United States' means the 50 States, the District of Columbia, the Commonwealth of Puerto Rico, any possession of the United States, the Commonwealth of the Northern Mariana Islands, and the Trust Territory of the Pacific Islands."
So clearly we can agree that, lawmakers know how to define “United States” accurately. Even section 7701 of Title 26 (Internal Revenue Code), which defines general terms for the IRC, uses a very specific definition which excludes most American citizens.
The same logic and understanding from the previous text is applicable in the definition of “trade or business” in 26 USC 79(a) which says:
(26) Trade or business
The term “trade or business” includes the performance of the functions of a public office.
This definition includes federal contractors, or anyone who is paid by the federal government. Regardless of any dictionary definition of a trade or business, the IRC defines that term as the performance of the functions of a public office.
The only people who are required to file and pay federal income taxes are therefore (1) citizens and residents of Washington D.C.About 99% of Americans are not required to file and pay federal income tax, based on the law as its written.
The IRS is entirely dependent on the taxpayer filing a return. See this quote from former IRS Commissioners Fred Goldberg and Charles Rossotti (Source):
What’s critical here is that substantially all of the revenue increase does not come from IRS audits—it comes from taxpayers … when they file their returns.
By filing an income tax return, you admit to owing the IRS money (even if you don’t owe anything). You put the noose around your own neck. By filing, you give the IRS power to audit you, empty your bank account, steal your property, and put you in prison.
If you’re part of the 99% that are legally not required to file and pay federal income tax, you don’t have to claim anything — you just don’t file a tax return.
If your employer requires you to fill out an IRS Form W-4 as a condition of employment or payment, and you are not a resident of DC nor a federal employee/contractor, you may provide your employer an amended W-4 Exempt form package. This form includes:
You can find this amended W-4 form, alongside additional information on the W4 Withholding Package page.
Based on the findings above, 99% of Americans are not legally required to file and pay federal income taxes. Here are some things to keep in mind when asking this question.
The IRS is entirely dependent on you admitting that you owe them money. If you do not file and therefore do not claim to owing money, the IRS is highly unlikely to pursue you.
There are ~80 million income tax non-filers in America, and the IRS is already struggling to keep up with filers who voluntarily agree to pay taxes. Forced collections have dropped by ~93% since 2011, and regardless, pursuing non-filers is not profitable for the IRS (2.25x return) compared to collections from filers (300x return).
Learn more about the IRS’ bluffs here.
The petitions state your findings of federal income taxes in clear terms, and ask your representatives to correct you if they deem them inaccurate. The right to petition your elected officials is protected by the First Amendment:
Congress shall make no law respecting … the right of the people peaceably to assemble, and to petition the Government for a redress of grievances.
By sending petitions to Congress (and keeping the stamped certified mail receipts), you have a record of sending these documents to your representatives.
Your representatives will do one of the following:
This protects you from being charged with tax evasion or other charges, because you have a record that before you refused to file, you expressed to the government that you are open and willing to pay your “fair share” of taxes, if they can show you the law which compels you to do so. Since they cannot show you the law, you do not have to file.
If you are a Restore Freedom Plan member, Freedom Law School will send these petitions for you. Click here to learn more about the Restore Freedom Plan. If you are not a Restore Freedom Plan member and you’d like to send petitions yourself, you may use our free Petitions to Congress tool.
In the event that your tax situation necessitates legal action, we will provide representation for you. Additionally, should the outcome of a court case result in lost funds, we will reimburse any money taken by the IRS within 30 days.
Members of the Restore Freedom Plan enjoy several other benefits, as well:
Many states tie their income tax laws to federal income tax laws by adopting Internal Revenue Code definitions, calculating state tax as a percentage of federal taxes owed, or using other methods. This practice, referred to as “piggy-backing” by Freedom Law School, means most residents in these states may not owe additional state income taxes. Please refer to the map and information below or go to the Interactive State Income Tax Map.
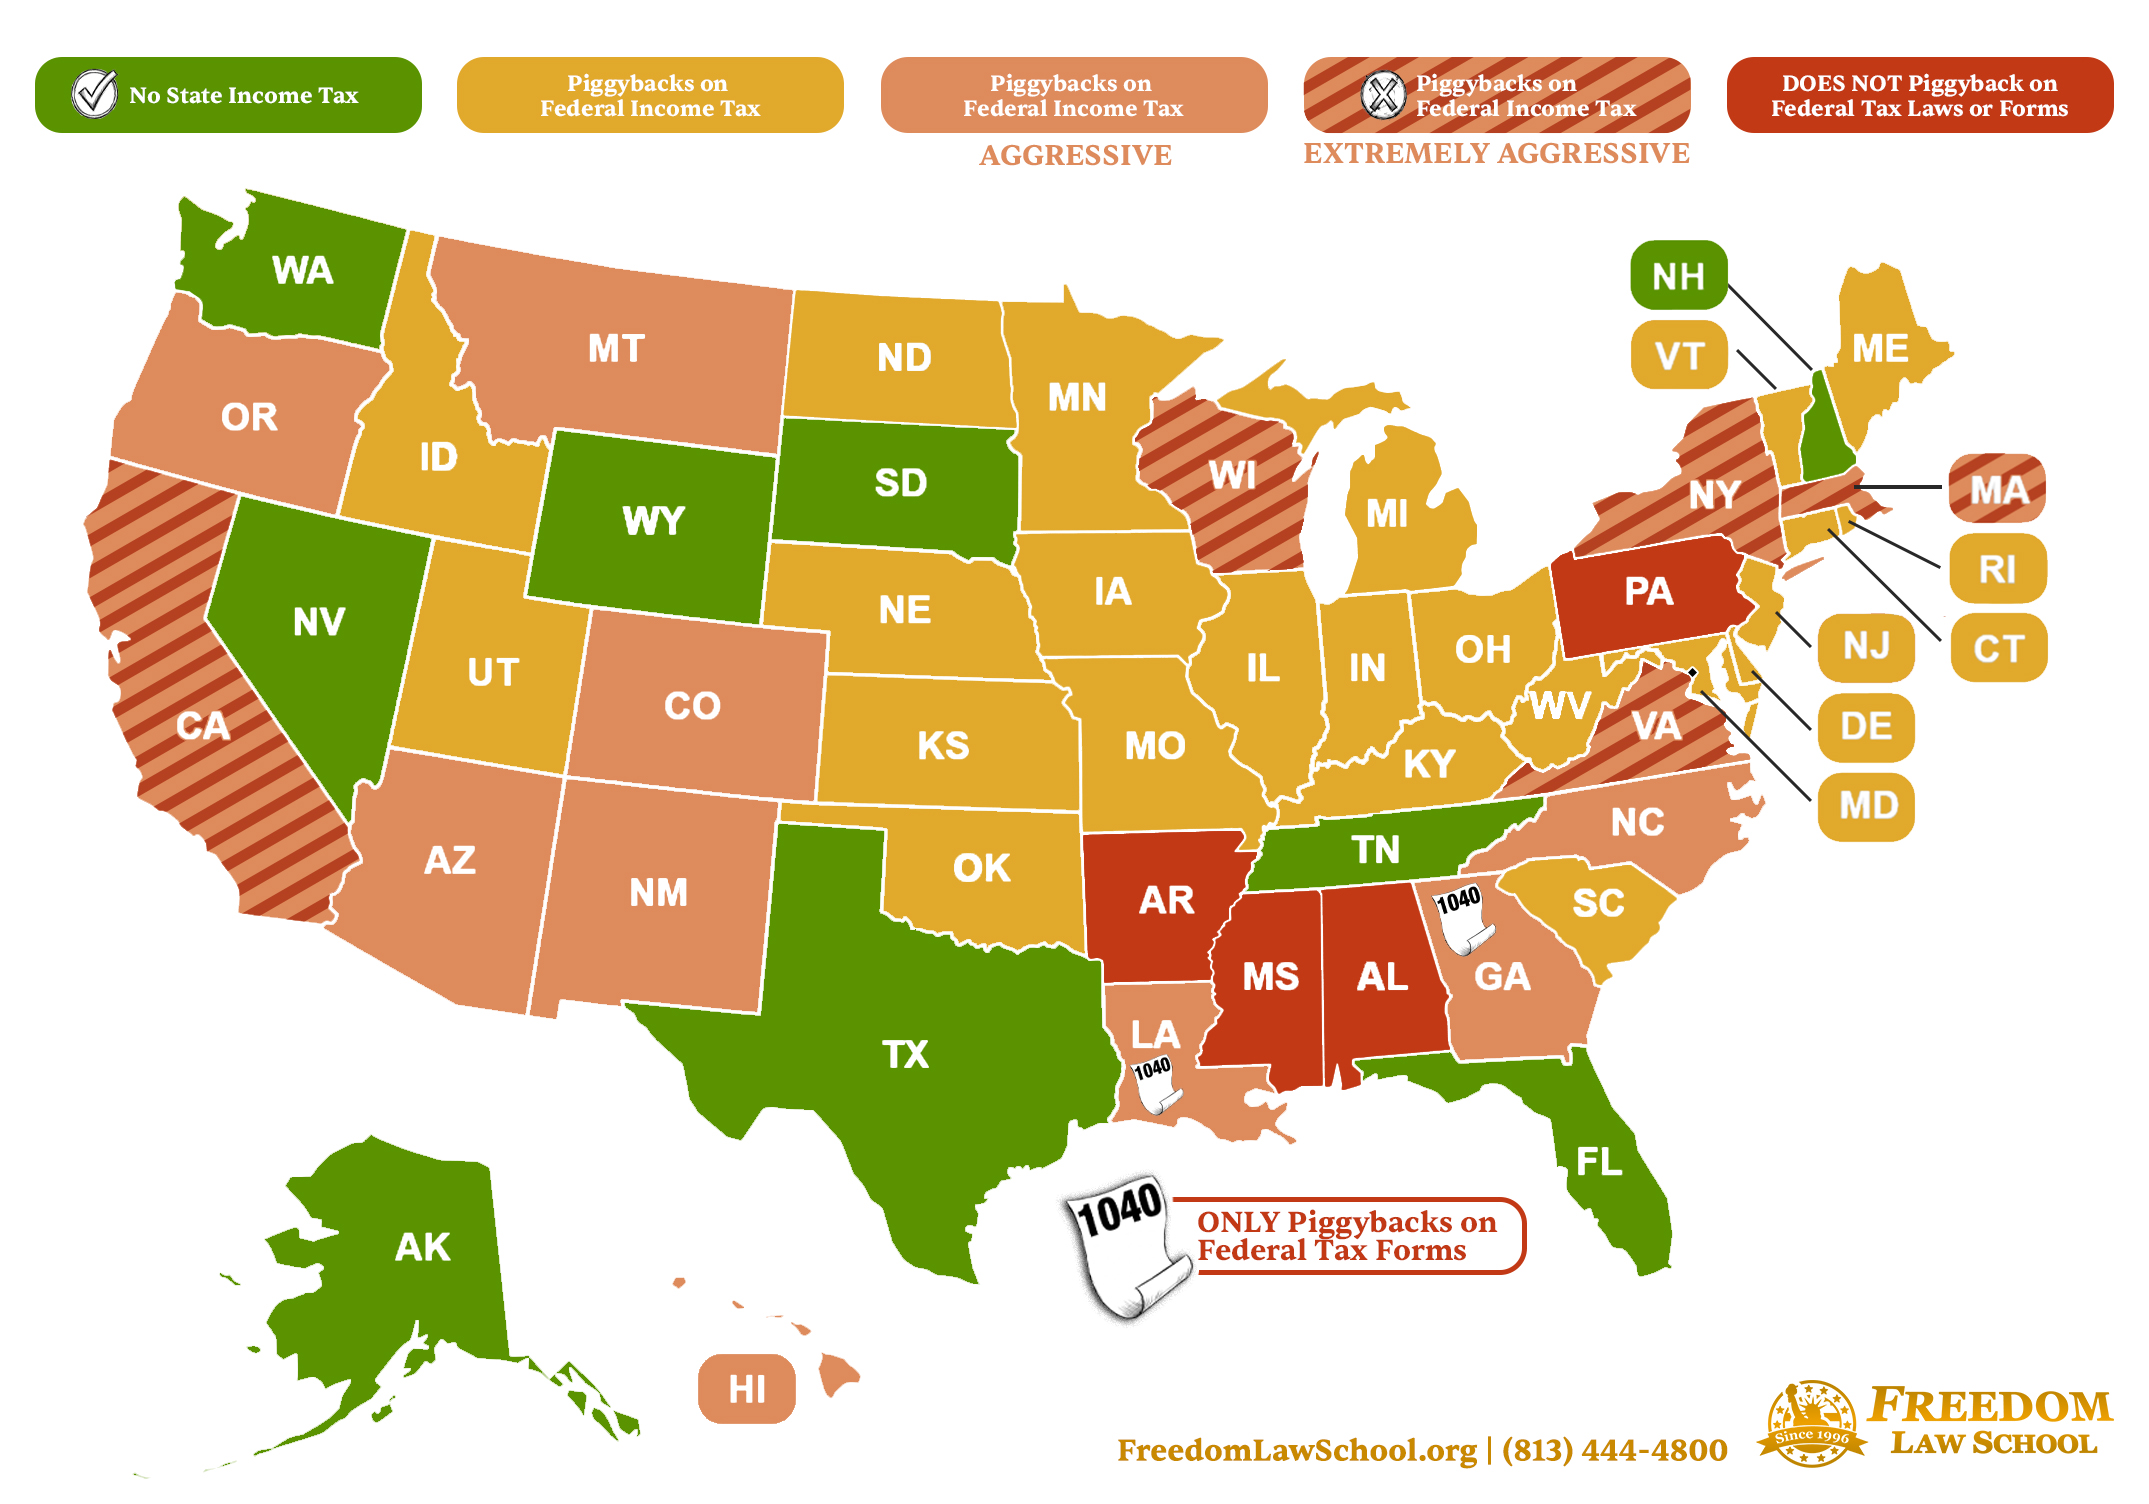
While our Restore Freedom Plan and Employer Freedom Plan do not cover state tax collections, our staff is available to assist students in responding to unwarranted collection attempts by state taxation agencies.
You don’t need to do anything! These states don’t have any income tax.
These states’ have an income tax which laws are based on the federal income tax laws.
State tax agency is known to be aggressive with collections +
State tax agency is known to be very aggressive with collections ++
These states’ income tax laws are independent from federal laws, and you cannot exempt from them.
If you have additional questions or concerns, call our office and ask directly by calling (813) 444-4800.
This case stated that the provisions of the 16th Amendment gave no new power of taxation to the federal government.
But, aside from the obvious error of the proposition, intrinsically considered, it manifestly disregards the fact that, by the previous ruling, it was settled that the provisions of the Sixteenth Amendment conferred no new power of taxation, but simply prohibited the previous complete and plenary power of income taxation possessed by Congress from the beginning from being taken out of the category of indirect taxation to which it inherently belonged…
In the interpretation of taxing statutes the government is unsupported in extending powers past the clear language of the law. When the government’s power to tax is questioned, the court is to strongly favor the citizen.
In the interpretation of statutes levying taxes, it is the established rule not to extend their provisions by implication beyond the clear import of the language used, or to enlarge their operations so as to embrace matters not specifically pointed out. In case of doubt, they are construed most strongly against the government and in favor of the citizen.
If a glossary of terms is provided with a law, the definitions of the terms listed override their typical meaning.
In such circumstances definition by the average man or even by the ordinary dictionary with its studied enumeration of subtle shades of meaning is not a substitute for the definition set before us by the lawmakers with instructions to apply it to the exclusion of all others. … There would be little use in such a glossary if we were free in despite of it to choose a meaning for ourselves.
The term “United States” can mean…
The term “United States” may be used in any one of several senses. It may be merely the name of a sovereign occupying the position analogous to that of other sovereigns in the family of nations. It may designate the territory over which the sovereignty of the United States extends, or it may be the collective name of the states which are united by and under the Constitution.
It is self-evident that in regard to the law, a definition of a term excludes unstated meanings.
Nor do we agree with the District Court’s assertion that Congress’ use of the term “political propaganda” was “a wholly gratuitous step designed to express the suspicion with which Congress regarded the materials.” … It is axiomatic that the statutory definition of the term excludes unstated meanings of that term. … As judges, it is our duty to construe legislation as it is written, not as it might be read by a layman, or as it might be understood by someone who has not even read it.
When a statute includes an explicit definition, we must follow that definition, even if it varies from that term’s ordinary meaning. Meese v. Keene, 481 U. S. 465, 484-485 (1987) (“It is axiomatic that the statutory definition of the term excludes unstated meanings of that term”); Colautti v. Franklin, 439 U. S., at 392-393, n. 10 (“As a rule, ‘a definition which declares what a term “means” … excludes any meaning that is not stated’ “)
While the term “includes” may sometimes be taken as synonymous with “means,” it may be used also as the equivalent of “comprehends” or “embraces.” Therefore, under § 200(a), the phrase “taxable year” may, where the context requires it, be taken to embrace all fractional parts of the taxable year;
Forcing Americans to submit an income tax form violates their Fifth Amendment right to refrain from providing any information to the government that could be used against them in prosecution.
(a) The privilege against self-incrimination guaranteed by the Fifth Amendment extends not only to answers that would in themselves support a conviction under a federal criminal statute, but also to those which would furnish a link in the chain of evidence needed to prosecute the claimant for a federal crime. Blau v. United States, 340 U. S. 159. P. 341 U. S. 486.
Information on documents voluntarily given to banks and seen by their employees in regular business isn’t protected by the Fourth Amendment, and sharing information with a third party (such as a bank) removes the expectation of privacy under the Fourth Amendment.
(b) There is no legitimate “expectation of privacy” in the contents of the original checks and deposit slips, since the checks are not confidential communications, but negotiable instruments to be used in commercial transactions, and all the documents obtained contain only information voluntarily conveyed to the banks and exposed to their employees in the ordinary course of business. The Fourth Amendment does not prohibit the obtaining of information revealed to a third party and conveyed by him to Government authorities.
In tax laws and other federal laws, the term United States can have different meanings depending on the specific legal section. A common assumption is that the term includes all 50 States, but this isn't always the case. To understand the correct application of a law, you must refer to the definitions provided within that specific law or chapter, as they can change.
Because the term United States has different definitions depending on the law, it is argued that for tax purposes the 1040 US Individual Income Tax Return applies only to those who are a citizen or resident of the District of Columbia. Therefore, the people in the 50 States are not legally required to file this form or pay income tax.
When you stop filing tax returns, the IRS may send a series of letters. It is important to understand what these letters mean and how you should respond.
You have legal protections against the IRS, with the most significant being the right to a trial. By requesting a Collection Due Process hearing and, if necessary, petitioning the Tax Court, you can legally challenge the IRS. The IRS is prohibited from taking any of your property while your case is in Tax Court.
There are Mortgage Brokers who do not need to see tax returns, and there are absolutely ones that are 100% legit! For example, see this very helpful explanation, “No Tax Returns? No Problem”, by Scott Smith of New Destiny Mortgage.
Many of our FLS members have been successful in becoming home owners without providing tax returns.
Yes! Mailing cash is safe, as long as you send it through the United States Postal Service (USPS), and not through a private courier such as FedEx or UPS. Tampering with U.S. Mail is a federal criminal offense. Private shipment companies are not protected in this way.It is incorrectly believed that cash cannot be shipped through the U.S. postal services and that is not true. You can read more about the post office’s stance on mailing currency here.
Freedom Law School has received packages from USPS for over two decades with no significant mishaps. Due to our recent growth, however, we have changed our shipping protocol to require the Registered® mailing service for additional security. Instructions can be found below.
To send mail, use the United States Postal Service (USPS) and send all correspondence to:
Freedom Law School
Box 10599
Brooksville, FL 34603
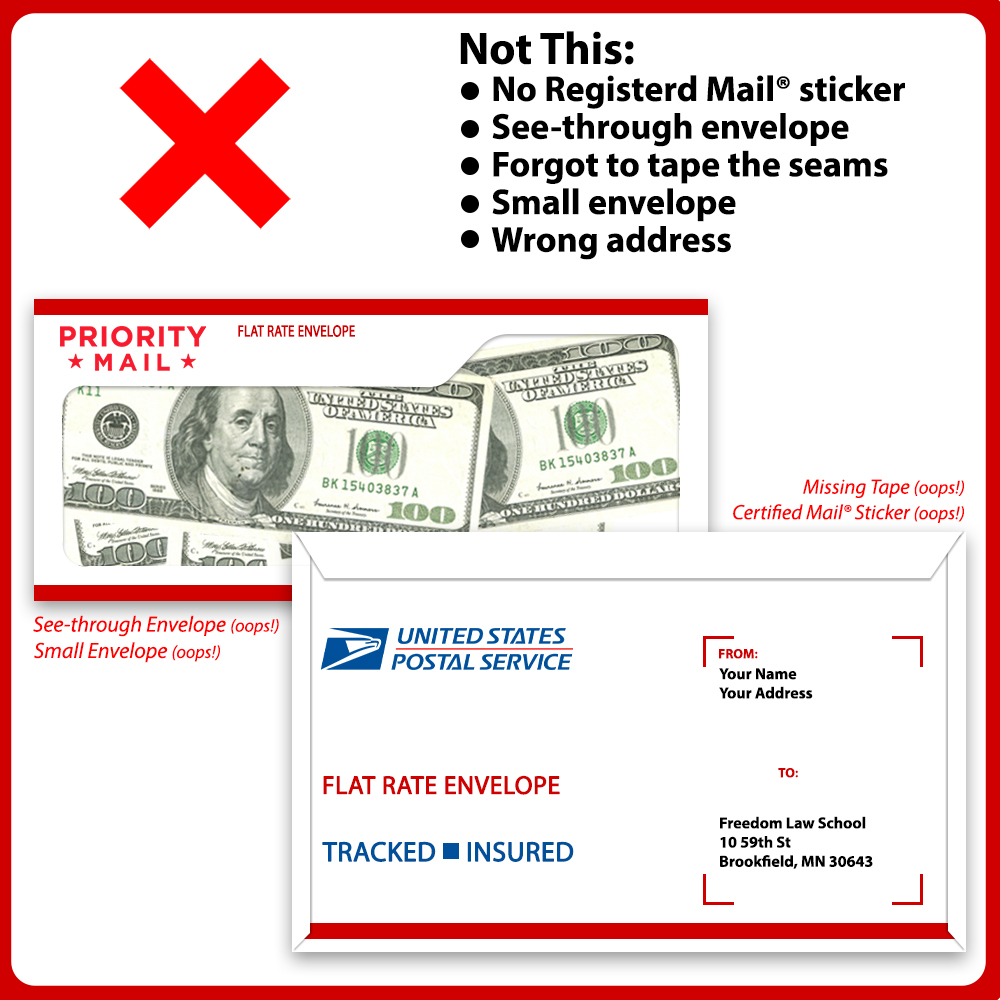
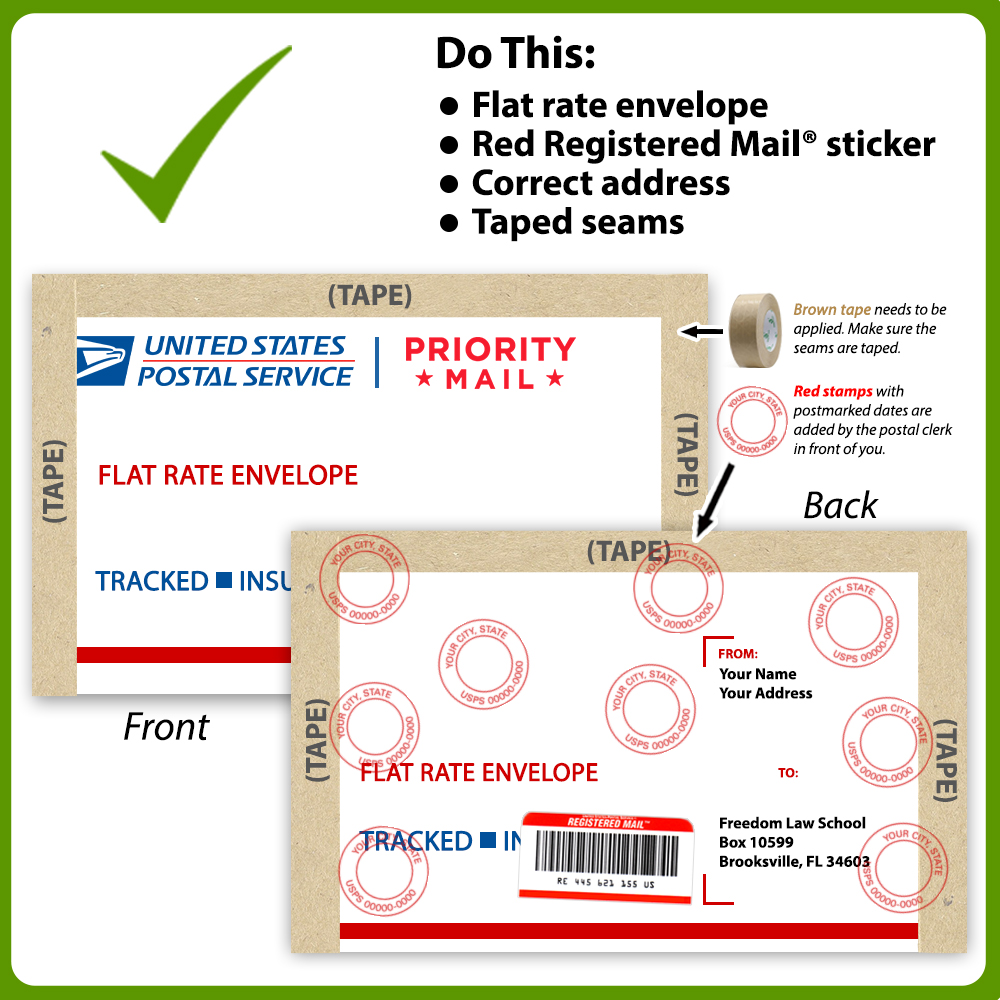
For secure delivery of packages, the organization recommends using USPS Registered Mail. To ensure the package is delivered properly and is the responsibility of Freedom Law School, you must follow these specific criteria:
Failure to follow these steps means you are fully responsible for any lost or missing contents.
For more detailed instructions on sending mail and packages, please visit the official source: Freedom Law School: Sending Mail
Unfortunately, due to regulations, you MUST submit your current address (which can be a PO box or private mailbox) to the IRS. The purpose of keeping your address current is to enable you to legally combat actions the IRS may take against you. If you do not, the IRS can claim, for example, that they sent you collections documents yet you never responded refuting their collections efforts.
Overview:Do you want to be able to pay zero estate taxes—no matter how huge your estate may be, even into the billions of dollars—legally and safely?
When dealing with a large inheritance, accountants, CPAs, and tax attorneys will inevitably point to the IRS's minimum filing thresholds (roughly $14 million in 2025 and $15 million in 2026) and advise you to file and pay federal estate taxes. They blindly follow the IRS's assumptions, often costing grieving families millions of dollars.
However, a strict reading of the Internal Revenue Code (Title 26) and U.S. Supreme Court precedent reveals a shocking truth: the federal estate tax, as defined by positive law, does not legally apply to the people of the 50 sovereign states.
For over 30 years, Freedom Law School founder Peymon Mottahedeh has successfully educated Americans on how to legally free themselves from deceptive federal taxation. Here is the step-by-step statutory proof showing why you do not owe the federal estate tax.
To understand who actually owes the estate tax, you must look at the exact wording of the law. The Internal Revenue Code (Title 26) is the "Bible" of the IRS, and the government publishes this code on its official legal website at uscode.house.gov.
Under 26 U.S.C. § 2001 (Imposition and Rate of Tax), the law clearly states exactly who is subject to the tax:
"A tax is hereby imposed on the transfer of the taxable estate of every decedent who is a citizen or resident of the United States."
This exact phrasing is mirrored on IRS Form 706 (the United States Estate Tax Return). Right below the main headline, the form clearly states that it is for the "Estate of a citizen or resident of the United States."
Naturally, most people assume that being a citizen of Florida, Texas, or California makes them a "citizen or resident of the United States." But in federal tax law, words have highly specific, restricted definitions.
To find out what the "United States" actually means for the estate tax, we must look at the definitions section of the Internal Revenue Code. Congress deliberately hides these definitions at the very end of the massive 10,000-page tax code, knowing that few CPAs or tax attorneys will ever bother to look them up.
Under 26 U.S.C. § 7701 (Definitions), Congress explicitly defines the geographic boundaries of their tax laws:
If you substitute the legal definition of "State" back into the definition of "United States," it reads: The term 'United States' includes only the District of Columbia and the District of Columbia.
Noticeably absent from these definitions are the 50 sovereign states. The term "United States" in the Internal Revenue Code legally refers only to the District of Columbia. Therefore, the federal estate tax imposed in § 2001 strictly applies to a citizen or resident of Washington, D.C.
Can the IRS simply ignore these definitions and assume the 50 states are included anyway? According to the U.S. Supreme Court, absolutely not.
In the 2000 Supreme Court case Stenberg v. Carhart, the Court established a strict and mandatory rule for how laws must be read:
"When a statute includes an explicit definition, we must follow that definition, even if it varies from that term's ordinary meaning."
The Court went on to explain that it is "axiomatic" (self-evident and undeniable) that a statutory definition excludes any unstated meanings. Because the 50 sovereign states were deliberately left unstated and excluded from the legal definition of the "United States" in Section 7701, the IRS has no legal authority to apply the estate tax to them. The ordinary, everyday meaning of the word is thrown out the window.
Another common tactic used by the IRS and misinformed accountants is to claim that the 50 states are "implied" to be included in the tax code. The U.S. Supreme Court completely struck down this argument in the unanimous 1917 decision Gould v. Gould:
"In the interpretation of statutes levying taxes, it is the established rule not to extend their provisions, by implication, beyond the clear import of the language used, or to enlarge their operations so as to embrace matters not specifically pointed out. In case of doubt, they are construed most strongly against the government, and in favor of the citizen."
The federal government cannot legally tax your estate by implication. Because the 50 sovereign states are not "specifically pointed out" in the legal definition of the "United States" for estate tax purposes, the law must be construed strictly against the government and in favor of the citizen.
Skeptics may still wonder if the exclusion of the 50 states was just a typo or a mistake. However, we have proof that Congress knows exactly how to include the 50 states when it wants to.
For example, look at the federal excise tax on petroleum under 26 U.S.C. § 4612. In this specific section, Congress explicitly broadens the definition of the United States to capture a wider tax base:
"...the term 'United States' means the 50 States, the District of Columbia, the Commonwealth of Puerto Rico... continental shelf areas, and foreign trade zones."
When Congress wants to legally tax the 50 states, they explicitly write "the 50 States" into the law. They deliberately left the 50 states out of the definitions for estate and income taxes. You cannot assume anything when it comes to federal tax laws.
The federal estate tax is legally a District of Columbia tax. Unless the decedent was a citizen or resident of Washington, D.C., their estate legally owes zero federal estate taxes, regardless of its size.
For decades, CPAs and attorneys have operated on fear and assumption, advising their clients to blindly pay millions—or even billions—of dollars to the IRS that they never legally owed. You do not have to volunteer your family's hard-earned legacy to the D.C. swamp.
A common misconception is that receiving a W-2 or 1099 form from an employer or third party automatically triggers a legal obligation to file a 1040 income tax form. Many believe that filing is the safest way to avoid IRS audits and prison. In reality, voluntarily signing and submitting a 1040 form increases your legal risks and traps you in a system you are not legally required to participate in.
When you sign a 1040 income tax form, you are signing it under penalties of perjury, swearing under oath that the information is true, correct, and complete.
The IRS relies on fear and propaganda because it lacks the manpower to enforce compliance across the board.
The Internal Revenue Code (Title 26) relies on highly specific legal definitions that differ entirely from ordinary English. Employers are deceived into sending W-2s and 1099s because they misunderstand these statutory terms.
If you received a W-2 or 1099, the ultimate goal is to correct the paperwork at the source so employers stop withholding your property and reporting it to the IRS.
When considering how to handle the IRS, it is vital to weigh the actual legal risks and benefits of submitting tax documents. For over 30 years, our Founder and President, Peymon Mottahedeh, has openly refused to file or pay federal income taxes and has successfully taught others how to legally and safely do the same.
Below is a breakdown of the realities behind the 1040 form so you can make an informed decision for your 2025 records.
The IRS operates using military principles found in Sun Tzu's The Art of War, specifically the tactic of subduing an enemy by making them believe they are weak while the enemy is strong. By convincing Americans to voluntarily sign the 1040 income tax confession form, the IRS wins without risking resources. The vast majority of the IRS's revenue is not generated from enforcement or audits, but rather from taxpayers voluntarily filing returns and confessing that they owe money.
Signing and submitting a 1040 form places you in immediate legal jeopardy.
Filing a 1040 form means you waive your 5th Amendment right to remain silent and voluntarily hand over all your private financial information for the government to use against you.
By signing the form under penalties of perjury, you are swearing under oath that everything is 100% true, correct, and complete.
You formally confess under oath that you have taxable income and owe the IRS the specified amount of money.
Filing puts the burden of proof entirely on your shoulders to justify all business expenses, deductions, and credits.
Submitting the form gives the IRS legal permission to audit you.
If you are audited or charged, you are forced to spend massive amounts of money hiring CPAs and tax attorneys for your defense.
For each 1040 form you file, you risk being charged with three separate tax crimes: attempting to evade a tax (5 years), filing fraudulent statements (3 years), and filing fraudulent returns (1 year), carrying a combined risk of up to nine years in prison.
IRS data books reveal that over 93% of the individuals the IRS sentences to prison are those who actually filed tax returns, whereas non-filers make up a tiny fraction of convictions.
Former IRS Criminal Investigation Division special agent Joe Banister confirmed that the IRS's standard procedure is to request a person's previously filed tax returns to use the information on those documents against them.
The legal defense for a filed return is so incredibly difficult that former U.S. Tax Court Judge Diane Kroupa chose to plead guilty and accept a 34-month prison sentence rather than attempt to defend the 1040 form she had submitted.
The money you surrender through this process is used to fund forever wars, protect pedophiles, and sustain federal government corruption.
For individuals holding digital assets, the 1040 form represents a specific and dangerous trap.
The 1040 form includes a direct question asking if you sold, exchanged, or liquidated any digital assets.
Answering "yes" automatically flags you for an aggressive IRS audit because the agency assumes all crypto transfers—even movements between your own private wallets—represent taxable gains.
Answering "no" when you have engaged in crypto transactions constitutes lying under oath, which exposes you to severe tax evasion and perjury charges.
The only notable benefit to filing a 1040 form is that you may potentially secure a slightly lower interest rate when borrowing money for a business loan or a real estate purchase.
Stepping out of the voluntary tax system eliminates the legal traps designed to ensnare filers.
There are virtually no risks to not filing, as the IRS actively leaves over 99.9% of non-filers completely alone.
When you do not file, you do not sign an oath confessing you owe money, meaning the IRS is forced to follow strict due process.
To pursue a non-filer, the IRS must create a formal tax proposal and issue a Notice of Deficiency, which grants you the right to challenge their claims in U.S. Tax Court with a full trial—a process that can tie them up for years.
Students who utilize the Restore Freedom Plan receive a firm guarantee: if you follow the law and the prescribed steps, you will stay out of prison, and if the IRS ever forcefully takes your money, we will reimburse you in full.
Instead of funding government corruption, your wealth remains with you to support freedom movements and the restoration of a free republic.
If you are a green card holder, you still do not have to file and pay income tax, unless you are a resident of Washington D.C. or you are performing work functions of the federal government.
No, you must have a drivers license, license plate, registration, etc. Roads are government built, maintained and funded roads.
Do not buy into patriot mythology. We love promoting freedoms, but some theories, even when they sound well-put, are simply wrong.
These are also protected under our guarantee same as any other income/investments. For those who are “mining” cryptocurrencies, make sure to include any amounts that you “mine” under the “self employed” section of our application. For any buying or selling of cryptocurrencies, make sure to include it in the appropriate section of the “capital gains” portion of our application to make sure it is covered by our guarantee. For any appreciation on its value, make sure to include that in the “interest and dividends” portion of the application.
Fear not! For many years Peymon has been accumulating his wisdom and strategies, documenting them, and passing them along to passionate activists who will one day be able to carry on Freedom Law School. You will not be stuck when Peymon passes away.
Richard Grant, once a student at Freedom Law School, ceased filing and paying income tax prior to his enrollment as a member. Subsequently, the IRS pressed criminal charges against Richard. However, he opted to engage a lawyer against FLS’ recommendations. Unfortunately, this decision left Richard inadequately prepared for his defense and lacking comprehension of IRS protocols, ultimately resulting in his prison sentence.
Several mainstream media outlets, including Forbes, have inaccurately and unjustly linked Richard’s imprisonment to Freedom Law School in an attempt to discredit FLS.
For W2 employees who have taxes withheld on their paychecks we recommend that you file a W4 tax exemption form and submit it to your HR department to stop withholding on your paycheck. This will need to be done every year. See our guide for more specific instructions.
Filing 1099 forms is not required for most Americans, and is simply a way that the IRS can collect information that they do not need to collect on taxes they are not owed.
This is preferable to being a W2 employee. Simply keep the 1099 you receive for your records (if you desire). If your contractor requires a W9 form, we recommend you fill that out normally but do not sign it. If your contractor requires that you do sign it, signing will not affect your eligibility for our 100% protection guarantee for our students.
There are many options in this situation, and the best approach could vary widely on many factors. Primarily we recommend teaching your employees about tax freedom. You should also consider our Employer Freedom Plan to protect your company and your employees. Please call to discuss your options on how this could work for your situation.
We recommend that you use independent contractors to fulfill your labor needs as you are able. We also recommend that you organize your company under an LLC to protect your personal assets. You should also consider our Employer Freedom Plan to protect your company from corrupt government collections.
As long as your business is conducted outside of D.C we recommend setting your company up under an LLC, and to simply stop filing under the corporation laws. There is no need to close out the corporation as it will be considered closed after a few years of no transactions.
Revocation of election to stop paying federal income tax is a patriot mythology. The process of revocation of election involves sending a letter to the IRS to revoke your election to pay income taxes for the rest of your life.
Freedom Law School does not deal with revocation of election, because it is not a successful legal strategy in practice.
In the income tax freedom movement, some alluring teachers use the term ‘[American] State National’ (aka “sovereign citizen”) to describe a fictitious citizenship status, aiming to liberate themselves from the constraints of U.S. law.
Sovereign citizens believe that the existing American governmental structure, including the courts and law enforcement, is illegitimate and that they retain an individual common law identity exempting them from the authority of those fraudulent government institutions. They may issue their own driver’s licenses and vehicle tags, create and file their own liens against government officials who cross them, question judges about the validity of their oaths, challenge the applicability of traffic laws to them, and in extreme cases, resort to violence to protect their imagined rights.
Sovereign citizens speak an odd quasi-legal language and believe that by not capitalizing names and by writing in red and using certain catchphrases, they can avoid any liability in the judicial system.
Read this excerpt from a State National promoter’s page:
As a completely unincorporated Person, a State National is sovereign and private and generally immune from prosecution until and unless they take some action that causes actual physical harm to someone else or someone else’s property, whereupon they are subject to the Common Law of the County and State where they live or where the alleged crime is committed. (Source)
You read that right, American state nationals and sovereign citizens claim that they are immune from prosecution unless they cause physical harm to person or property. Does this work? No.
Sovereign citizens’ tactics often succeed in delaying legal proceedings, and may occasionally confuse or exhaust public officials. However, their arguments are never upheld in court. (Source and Reference)
Can I claim sovereign citizenship? Does using a ZIP code make me part of DC? Does my name in CAPITAL LETTERS refer to my straw man? Am I out of the federal government’s jurisdiction?
These theories are what Freedom Law School refers to as “baseless legal theories” or “patriot mythologies.” With the ease of internet communications, these baseless theories spread like weeds, offering fantasy solutions to common Freedom and Tax Honesty Movement issues. They sound great, but in reality do not work. Unfortunately, in dealing with the corrupt IRS and U.S. government, there are no “silver bullet” miracle cures.
Ultimately, the focus is not solely on the technical accuracy of a theory, but rather on its practical effectiveness and likelihood of being upheld in court. The sovereign citizenship theory, like many others, does not work in practice. Rather than dabbling in a multitude of unfounded theories, stick with what has been proven effective. Check out Freedom Law School’s seven steps and our track record of court victories.
Irwin Schiff was a very honorable patriot to be commended for his work in the Tax-Honesty and Freedom Movements. Irwin however made mistakes and refused to accept advice from Peymon and others. While Irwin was technically 100% correct on the fact that there is no law requiring the average American to file and pay income taxes, he did not follow procedure to protect himself better from the corrupt court systems.
Wesley Snipes relied on something we warn you about at Freedom Law School: fake patriot mythology. Wesley Snipes did not get a prison sentence from following Freedom Law School’s advice. He relied on the false advice of Eddie Kahn and mailed in a fake, phony, fraudulent receipt to the IRS for taxes he owed, expecting a refund.
Zero returns are an attempt to get money back from the IRS after filing. The process involves filing a tax return with the IRS which shows zero income.
This method is advocated by Pete Hendrickson, notably in his book “Cracking The Code” and on his website, Lost Horizons. Both Pete Hendrickson and his wife, Doreen, were sentenced to prison after using this method. (Source.)
They may work to get money back from the IRS, but are not recommended by Freedom Law School because it defeats the purpose of not filing, and involves lying on a return which exponentially increases your chances of being pursued by the IRS.

Overview:Do you want to be able to pay zero estate taxes—no matter how huge your estate may be, even into the billions of dollars—legally and safely?
When dealing with a large inheritance, accountants, CPAs, and tax attorneys will inevitably point to the IRS's minimum filing thresholds (roughly $14 million in 2025 and $15 million in 2026) and advise you to file and pay federal estate taxes. They blindly follow the IRS's assumptions, often costing grieving families millions of dollars.
However, a strict reading of the Internal Revenue Code (Title 26) and U.S. Supreme Court precedent reveals a shocking truth: the federal estate tax, as defined by positive law, does not legally apply to the people of the 50 sovereign states.
For over 30 years, Freedom Law School founder Peymon Mottahedeh has successfully educated Americans on how to legally free themselves from deceptive federal taxation. Here is the step-by-step statutory proof showing why you do not owe the federal estate tax.
To understand who actually owes the estate tax, you must look at the exact wording of the law. The Internal Revenue Code (Title 26) is the "Bible" of the IRS, and the government publishes this code on its official legal website at uscode.house.gov.
Under 26 U.S.C. § 2001 (Imposition and Rate of Tax), the law clearly states exactly who is subject to the tax:
"A tax is hereby imposed on the transfer of the taxable estate of every decedent who is a citizen or resident of the United States."
This exact phrasing is mirrored on IRS Form 706 (the United States Estate Tax Return). Right below the main headline, the form clearly states that it is for the "Estate of a citizen or resident of the United States."
Naturally, most people assume that being a citizen of Florida, Texas, or California makes them a "citizen or resident of the United States." But in federal tax law, words have highly specific, restricted definitions.
To find out what the "United States" actually means for the estate tax, we must look at the definitions section of the Internal Revenue Code. Congress deliberately hides these definitions at the very end of the massive 10,000-page tax code, knowing that few CPAs or tax attorneys will ever bother to look them up.
Under 26 U.S.C. § 7701 (Definitions), Congress explicitly defines the geographic boundaries of their tax laws:
If you substitute the legal definition of "State" back into the definition of "United States," it reads: The term 'United States' includes only the District of Columbia and the District of Columbia.
Noticeably absent from these definitions are the 50 sovereign states. The term "United States" in the Internal Revenue Code legally refers only to the District of Columbia. Therefore, the federal estate tax imposed in § 2001 strictly applies to a citizen or resident of Washington, D.C.
Can the IRS simply ignore these definitions and assume the 50 states are included anyway? According to the U.S. Supreme Court, absolutely not.
In the 2000 Supreme Court case Stenberg v. Carhart, the Court established a strict and mandatory rule for how laws must be read:
"When a statute includes an explicit definition, we must follow that definition, even if it varies from that term's ordinary meaning."
The Court went on to explain that it is "axiomatic" (self-evident and undeniable) that a statutory definition excludes any unstated meanings. Because the 50 sovereign states were deliberately left unstated and excluded from the legal definition of the "United States" in Section 7701, the IRS has no legal authority to apply the estate tax to them. The ordinary, everyday meaning of the word is thrown out the window.
Another common tactic used by the IRS and misinformed accountants is to claim that the 50 states are "implied" to be included in the tax code. The U.S. Supreme Court completely struck down this argument in the unanimous 1917 decision Gould v. Gould:
"In the interpretation of statutes levying taxes, it is the established rule not to extend their provisions, by implication, beyond the clear import of the language used, or to enlarge their operations so as to embrace matters not specifically pointed out. In case of doubt, they are construed most strongly against the government, and in favor of the citizen."
The federal government cannot legally tax your estate by implication. Because the 50 sovereign states are not "specifically pointed out" in the legal definition of the "United States" for estate tax purposes, the law must be construed strictly against the government and in favor of the citizen.
Skeptics may still wonder if the exclusion of the 50 states was just a typo or a mistake. However, we have proof that Congress knows exactly how to include the 50 states when it wants to.
For example, look at the federal excise tax on petroleum under 26 U.S.C. § 4612. In this specific section, Congress explicitly broadens the definition of the United States to capture a wider tax base:
"...the term 'United States' means the 50 States, the District of Columbia, the Commonwealth of Puerto Rico... continental shelf areas, and foreign trade zones."
When Congress wants to legally tax the 50 states, they explicitly write "the 50 States" into the law. They deliberately left the 50 states out of the definitions for estate and income taxes. You cannot assume anything when it comes to federal tax laws.
The federal estate tax is legally a District of Columbia tax. Unless the decedent was a citizen or resident of Washington, D.C., their estate legally owes zero federal estate taxes, regardless of its size.
For decades, CPAs and attorneys have operated on fear and assumption, advising their clients to blindly pay millions—or even billions—of dollars to the IRS that they never legally owed. You do not have to volunteer your family's hard-earned legacy to the D.C. swamp.